Disclosure: some links in this post are referral links. If you open an account through them, CentsForward may earn a commission at no extra cost to you. Read the full affiliate disclosure.
The first dividend lands in your broker account and it feels like proof. Money arrived while you were at work, asleep, doing nothing. Then you look closer and notice a line you never saw in any YouTube video: “withholding tax,” and it took almost a third of the payment.
That moment is why most dividend investing for beginners advice fails people outside the US. It was written for Americans, with American tax rules, American accounts, and American funds. This guide is the version for everyone else.
In this guide:
- What Dividend Investing Actually Is
- The 30% Tax Most Beginners Outside the US Miss
- The Dividend Illusion: Why Payouts Feel Better Than They Are
- Dividend Investing for Beginners: 7 Steps for Non-Americans
- Costly Mistakes to Avoid
- Frequently Asked Questions
The short answer: dividend investing means owning shares or funds that pay you part of their profits in cash. If you live outside the US, the smartest way to start is usually through Ireland-domiciled UCITS ETFs rather than US-listed funds, because they cut the tax taken from your dividends and avoid US estate tax exposure. Choose a broker that accepts your country, decide whether you want income now or growth later, and automate small monthly investments.
What Dividend Investing Actually Is
A dividend is a cash payment a company makes to its shareholders, usually from profits. Many large, stable companies pay them every quarter. You get paid simply for owning the shares.
Dividend yield is the yearly dividend divided by the share price. A fund priced at $100 that pays $3 a year has a 3% yield. If you own $10,000 of it, that is roughly $300 a year before tax.
The ex-dividend date is the cutoff. You must own the shares before that date to receive the next payment. Buy on or after it and the dividend goes to the previous owner.
The 30% Tax Most Beginners Outside the US Miss
When a US company pays a dividend to someone who is not a US person, the US takes tax first. The default rate is 30%. Countries with a tax treaty with the US often get that reduced to 15%, which you claim by filing a short form called the W-8BEN with your broker.
Here is the part almost nobody explains. The rate depends on where you are tax resident, not on your passport. The UAE has no income tax treaty with the US, so a UAE resident holding US dividend stocks or US-listed ETFs usually pays the full 30%, whatever their nationality.
On that $10,000 example, a 3% yield gives you $300. At 30% withholding, $90 disappears before it reaches you. Over 20 years of reinvesting, that leak compounds into real money.
How do Irish UCITS ETFs reduce the tax?
A UCITS ETF is a fund built under European rules, and many of the biggest ones are domiciled in Ireland. Ireland has a treaty with the US, so the fund itself pays 15% on US dividends instead of 30%. Ireland generally does not add its own withholding when the fund pays non-Irish investors.
US-listed ETFs also count as US assets, and non-residents can face US estate tax on US assets above $60,000. Irish UCITS ETFs are generally not treated as US assets, so your family is not exposed to that risk. I explain this in more depth in UCITS ETFs explained for non-US investors.
The Dividend Illusion: Why Payouts Feel Better Than They Are
Dividends feel like free money. They are not. On the ex-dividend date, the share price usually drops by roughly the amount paid out, because that cash has left the company.
Your brain treats a dividend as income and a price rise as “just numbers on a screen.” Psychologists call this mental accounting, and it pushes beginners toward high-yield stocks even when the total return is worse. What builds wealth is total return: price growth plus dividends, minus tax and fees.
This does not make dividends bad. A steady payout can keep you invested through a scary market, and staying invested is half the battle. Just choose dividends because they suit your goal, not because the cash feels good.
Dividend Investing for Beginners: 7 Steps for Non-Americans
Step 1: Decide whether you want income now or growth later
If you want cash coming in today, choose distributing funds, which pay dividends out to you. If you are in your 20s or 30s and building wealth, accumulating funds usually make more sense. They reinvest dividends automatically inside the fund, so nothing sits idle and you never have to act.
Most beginners lean toward income because it feels real. Ask yourself honestly whether you need that cash now, or whether you would just reinvest it anyway.
Step 2: Check your tax residency, not your passport
Work out which country you are tax resident in and whether it has a US tax treaty. If you live in the UAE, assume 30% on US dividends held directly. If you live in a treaty country, you may qualify for 15% once your W-8BEN is on file.
This is the detail most guides skip: where you live decides your dividend tax, not where you are from.
Step 3: Open an account with a broker that accepts you
Fidelity, Schwab, and Vanguard’s US platform will not open accounts for most non-US residents. You need a broker built for international investors, and the W-8BEN is usually handled during signup.
Interactive Brokers gives you access to the London Stock Exchange, where most Irish UCITS ETFs trade, with low fees and an optional dividend reinvestment setting. You can open an Interactive Brokers account here. If you want a simpler app to start with smaller amounts, eToro is a beginner-friendly option, though check that the specific UCITS ETFs you want are available there before you fund the account.
Not sure which fits you? My comparison of the best brokers for non-US investors breaks down fees and market access, and this guide walks you through opening an Interactive Brokers account from abroad step by step. If you are starting from zero, begin with how to start investing from abroad.
Step 4: Choose Irish UCITS ETFs over US-listed dividend funds
Popular US dividend ETFs like SCHD and VYM are built for Americans, and once the 30% is taken they cost you more. Look for Ireland-domiciled funds instead. If halal investing matters to you, iShares runs a range of Shariah-screened UCITS ETFs that all pay dividends out. A few widely held examples, for research only and not a recommendation:
- ISWD: iShares MSCI World Islamic, distributing. Large Shariah-compliant companies across developed markets in one fund.
- ISUS: iShares MSCI USA Islamic, distributing. Shariah-screened US companies, wrapped in an Irish fund so you get the lower 15% dividend tax.
- ISDE: iShares MSCI Emerging Markets Islamic, distributing. Adds exposure to emerging economies.
Shariah-screened funds exclude companies with high debt or haram business activities, so they often hold fewer financial stocks and pay slightly lower yields than conventional funds. That trade-off is the point.
Always check the fund’s factsheet for domicile (“Ireland”), share class (distributing or accumulating), currency, and ongoing charge before you buy.
Step 5: Learn to read yield without chasing it
A healthy dividend yield for a broad fund is often somewhere between 1.5% and 4%. A single stock yielding 9% or 10% is often a warning sign, not a bargain. The price may have collapsed because the market expects the dividend to be cut.
This is called a yield trap. The high number pulls you in, the dividend gets cut, and the share price falls further.
Step 6: Reinvest automatically
Reinvesting is where dividends turn into real wealth, because each payment buys more shares that pay more dividends. This is compound interest doing the heavy lifting.
The simplest way is an accumulating fund, which does it for you. If you hold distributing funds, turn on your broker’s dividend reinvestment option, or add the cash to your next monthly purchase.
Step 7: Automate a monthly amount and leave it alone
Pick an amount you can invest every month without touching your emergency savings, even $200 to start. Set it up on the same day your salary lands, before you have a chance to spend it.
If you have not built a safety net yet, do that first. Here is how big an emergency fund expats really need, since losing your job abroad can also mean losing your visa.
Costly Mistakes to Avoid
- Buying US-listed ETFs by default. They are what every American guide recommends, and they cost non-residents more in tax and estate risk.
- Chasing the highest yield. Total return matters more than the size of the payout.
- Forgetting the W-8BEN. Without it, you may pay 30% even if your country has a treaty. It also needs renewing, usually every three years.
- Taking dividends as spending money too early. In your growth years, every dividend you spend is a share you never buy.
- Selling in a downturn. Dividend funds still fall in a crash. The people who build wealth are the ones who keep buying.
Frequently Asked Questions
Do UAE residents pay tax on dividends?
The UAE does not charge personal income tax on dividends. However, the country where the company is based may take tax before the dividend reaches you. US dividends paid directly to UAE residents are usually withheld at 30%, which is why Irish UCITS ETFs are popular with UAE investors.
Is dividend investing halal?
It can be: dividends themselves are generally considered permissible when the company’s business and finances pass Shariah screening. Islamic index funds like ISWD do that screening for you, and many scholars recommend purifying a small portion of dividends linked to any non-compliant income. Check with a scholar you trust for your own situation.
Should beginners choose accumulating or distributing funds?
If you do not need the income yet, accumulating funds are usually simpler and more efficient, because reinvestment happens automatically. Distributing funds suit people who want regular cash, such as those nearing retirement or living partly off their portfolio.
How much money do I need to start dividend investing?
Less than most people think. Many brokers let you start with a few hundred dollars, and some allow fractional shares. Consistency matters more than the starting amount.
The Bottom Line
Dividend investing works outside the US. It just works differently. The people who do well are not the ones with the highest yield, they are the ones who quietly stopped losing 30% to a tax they did not know existed, and kept buying every month.
Want one practical investing tip for non-Americans in your inbox each week? Join the free CentsForward newsletter.
This article is for education only and is not financial or tax advice. Tax rules change and depend on your personal situation, so check with a qualified professional before making decisions.
Keep reading
Buy an ETF on Interactive Brokers: 7 Proven Steps
Want to buy an ETF on Interactive Brokers without mistakes? Follow 7 proven steps from funding to your first limit order, plus halal account settings to check.
Halal ETFs: 3 Best UCITS Picks for Non-US Investors
Looking for halal ETFs outside the US? Compare 3 Irish-domiciled UCITS picks, their fees and screening, and learn how to choose one with confidence.
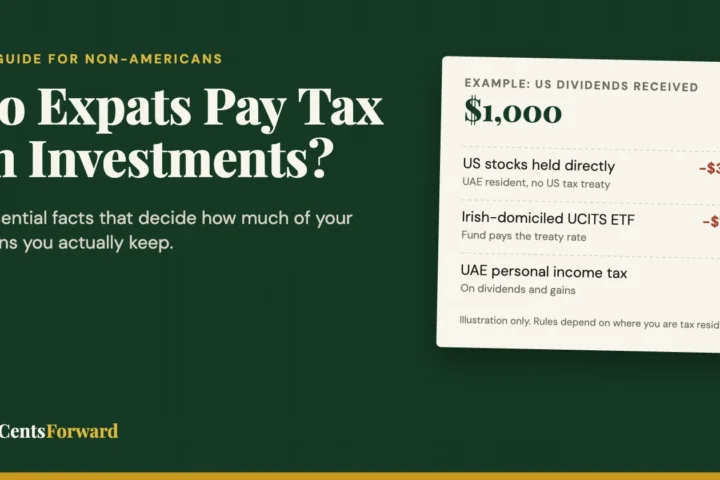
Do Expats Pay Tax on Investments? 7 Essential Facts to Avoid Costly Mistakes
Do expats pay tax on investments? Here is how residency, US withholding and estate tax really work for non-Americans, and how to keep more of your returns.
[…] You do not have to choose only one. Many investors start on eToro to learn, then move long-term holdings to IBKR once fees start to matter. Once your account is open, the next question is what to buy. Compare the two most popular global funds in VWRA vs VWRP, or read dividend investing for beginners outside the US. […]