Disclosure: some links in this post are referral links. If you open an account through them, CentsForward may earn a commission at no extra cost to you. Read the full affiliate disclosure.
You earn a good salary, you may live somewhere with zero income tax, and on paper you are in one of the best financial positions anyone could ask for. Then you search for how to start investing as an expat, and within ten minutes you are reading about Roth IRAs, 401(k) limits and brokers that want a US Social Security number. None of it applies to you, so you close the tab and promise yourself you will sort it out next month.
Expat investing is not harder than investing at home. It is just different, and almost nobody explains the differences clearly. This guide does, step by step, with real brokers, real costs and halal options, for anyone living and earning outside their home country.
The short answer: to start investing as an expat, build a small emergency fund first, open an account with an international broker that accepts your country of residence (such as Interactive Brokers, eToro or XTB), fund it in US dollars, and buy a low-cost, broadly diversified ETF every month. Irish-domiciled UCITS ETFs are usually the best fit for non-Americans because they cut US dividend tax and avoid US estate tax risk. Avoid long-term offshore savings plans sold by commission-based advisers.
In this guide:
- Why Expat Investing Is Different
- Expat Investment Options: What You Can and Cannot Use
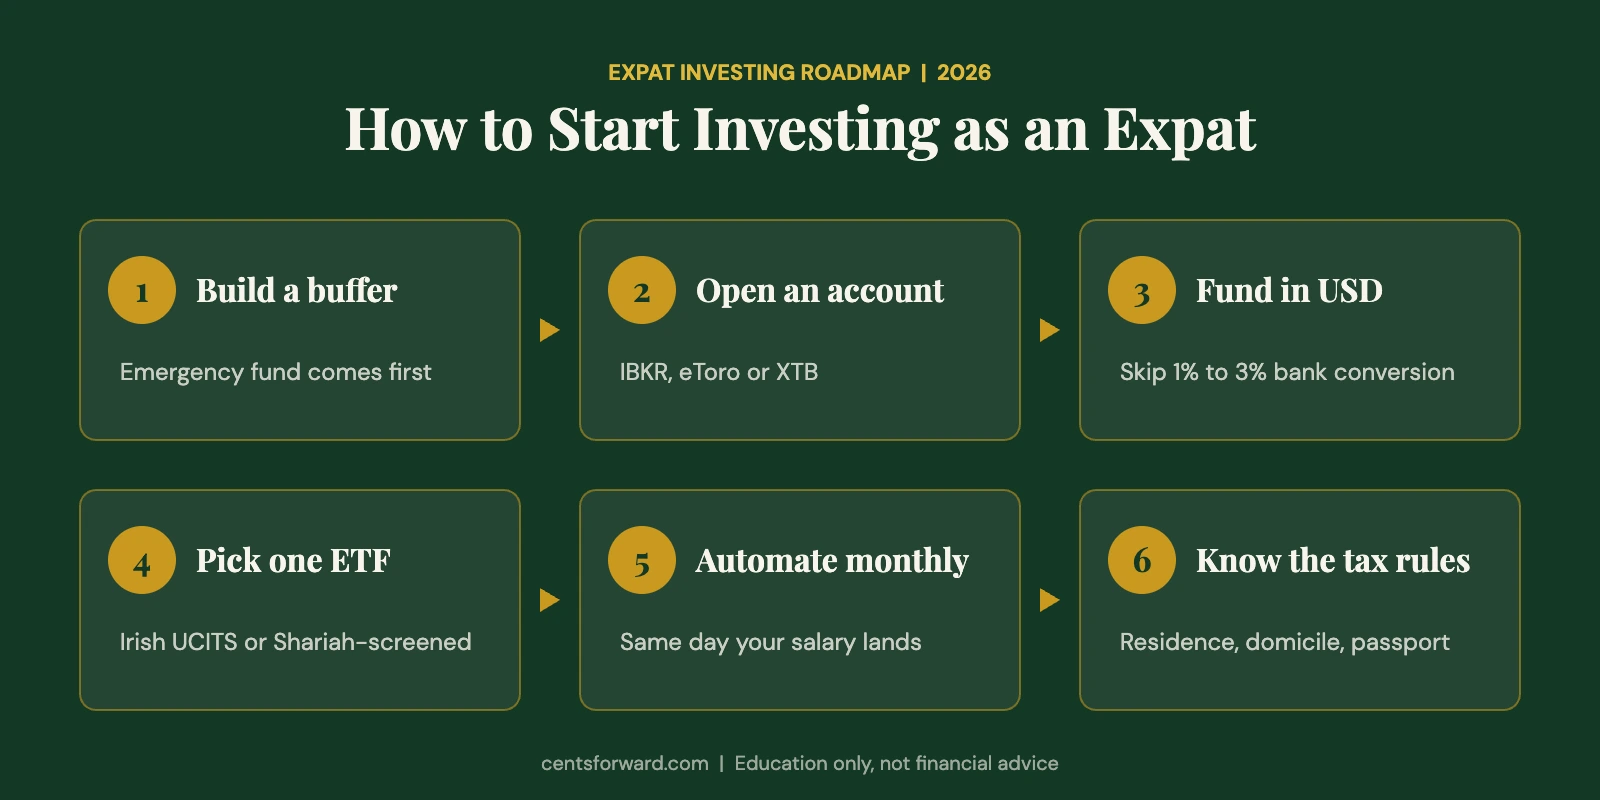
- Step 1: Build Your Foundation First
- Step 2: Open an Expat Brokerage Account
- Step 3: Fund Your Account in US Dollars
- Step 4: Choose Your First Investment
- Step 5: Automate a Monthly Amount
- Step 6: Understand the Tax Rules of Expat Investing
- Expat Investment Advice: The Offshore Plan Trap
- What Happens When You Move Countries?
- 4 Expat Investing Mistakes to Avoid
- Frequently Asked Questions
- The Bottom Line
Why Expat Investing Is Different
Most investing advice is written for someone with a permanent address in one Western country, access to tax-free retirement accounts and a single currency to think about. As an expat, you usually have none of that.
You have no employer pension in many Gulf countries, no ISA or IRA, and a residence that depends on your job. The country you live in sees you as temporary, and your home country may no longer see your finances as its concern.
What you do have is rare: often a higher income, little or no income tax, and the freedom to invest in global markets. Expat investing is about using those advantages while protecting yourself from the risks that come with being mobile: job loss, moving countries and currency changes.
Expat Investment Options: What You Can and Cannot Use
Your options are wider than most people think, but the access points are different.
What you can usually access as an expat:
- Global stocks through an international broker
- ETFs listed in London, Europe and the US
- Shariah-screened Islamic ETFs and funds
- Sukuk funds, the Islamic alternative to bonds
- Gold, through physically backed products
What you usually cannot access:
- US Roth IRA or 401(k), which require US tax residency
- UK ISAs, which require UK residency
- Many US brokers such as Robinhood, Fidelity and Schwab, which generally do not accept non-US residents
Losing access to tax-free wrappers sounds like a big loss. But if you live in a country with no personal income or capital gains tax, such as the UAE, your investments already grow without local tax while you live there.
Step 1: Build Your Foundation First
The first rule of expat investing is simple: before any money goes into the market, put two things in place, an emergency fund and zero high-interest debt.
For expats the emergency fund matters even more. In many countries, losing your job can also mean losing your visa, and you may need to cover rent, school fees or a flight home within weeks. Without a cash buffer, you may be forced to sell your investments at a loss at exactly the wrong time. Here is how big an emergency fund expats really need.
Not sure how much of your salary to set aside? This guide on how much of your salary to save as an expat gives clear targets, and the beginner investing checklist walks through every step before your first investment.
Step 2: Open an Expat Brokerage Account
This is the most important practical decision you will make. A good expat brokerage account accepts your country of residence, is properly regulated, lets you buy the funds you need, and ideally stays with you if you move. Three platforms stand out.
Interactive Brokers (IBKR): best for long-term expats
IBKR accepts clients from around 200 countries and connects to more than 150 markets, including the London Stock Exchange where most UCITS ETFs trade. There is no minimum deposit, US stocks cost $0.005 per share with a $1 minimum, and UAE clients are served by a DFSA-regulated branch in Dubai. The platform takes time to learn, but it is the most portable option if you might move. You can open an Interactive Brokers account here, and this guide shows you how to open an IBKR account from abroad.
eToro: best for complete beginners
eToro has the simplest app, fractional shares from $10 and 0% commission on non-leveraged ETF purchases. UAE residents need a $100 first deposit and are served by eToro (ME) Limited, regulated by the FSRA in Abu Dhabi. An Islamic account is available. Stick to real shares and ETFs, not CFDs or leverage. You can open an eToro account here.
eToro is a multi-asset investment platform. The value of your investments may go up or down. Your capital is at risk.
XTB: best for zero commission
XTB charges 0% commission on stocks and ETFs up to €100,000 of monthly turnover, has no minimum deposit and offers an Islamic swap-free account. In the UAE it is regulated by the DFSA and also holds a licence from the UAE Capital Market Authority. Currency conversion costs 0.5%, so funding in US dollars helps. You can open an XTB account here.
For a full side-by-side of fees, regulation and halal options, read the best brokers for non-US investors.
What about local bank investment platforms?
Banks in the Gulf offer investment platforms, but fees are usually higher and the fund range smaller. Use your bank to send money to your broker, not as your main investing account.
What you need to open an account
- Passport
- Residence visa or national ID of your country of residence (for example, Emirates ID)
- Proof of address, such as a utility bill or bank statement
- A W-8BEN form, which confirms you are not a US person. The broker handles this during sign-up.
Step 3: Fund Your Account in US Dollars
Currency is the hidden cost of expat investing that most beginners ignore. If you earn in dirhams or riyals, both are pegged to the US dollar, so currency risk on USD investments is low. The real cost is the conversion itself.
Banks and card deposits often charge 1% to 3% to convert local currency into dollars. On $10,000 a year, that is up to $300 lost before you buy anything. A multi-currency account such as Wise converts at the real exchange rate with a small, transparent fee, and lets you send USD straight to your broker.
If you plan to retire somewhere else, think about the currency you will spend later. Most expats keep the core of their portfolio in US dollar assets because the dollar is the most widely used currency for global investing.
Step 4: Choose Your First Investment
This is where most people new to expat investing freeze. The simple answer for most beginners is one broad, diversified ETF.
An ETF (exchange-traded fund) holds hundreds or thousands of companies in one investment. Buy one share and you own a small piece of all of them, without researching each company.
Why Irish UCITS ETFs suit expats
US-listed ETFs carry two problems for non-Americans. First, the US withholds 30% of dividends for residents of countries without a US tax treaty, including the UAE. Irish-domiciled UCITS ETFs pay 15% at the fund level instead. Second, US-listed funds count as US assets, and non-residents can face US estate tax on US assets above $60,000. Irish funds avoid that risk. I explain both in UCITS ETFs explained.
Halal ETF options for expats
If you want your portfolio to follow Islamic principles, several Irish-domiciled Shariah-screened ETFs are available on London exchanges:
- ISWD: iShares MSCI World Islamic UCITS ETF. Large companies across developed markets, screened for Shariah compliance.
- ISUS: iShares MSCI USA Islamic UCITS ETF. Shariah-screened US companies.
- ISDE: iShares MSCI Emerging Markets Islamic UCITS ETF. Shariah-screened emerging market companies.
These are examples for research, not recommendations. Before buying, check the factsheet for the domicile (Ireland), currency, ongoing charge and screening method. Many scholars also recommend purifying the small share of dividends linked to non-compliant income. For more on income funds, read dividend investing for beginners outside the US.
Should you start with individual stocks?
Not yet. Single stocks need company research and carry much higher risk. A broad ETF gives you market returns while you learn. Once you have a solid base, you can add individual stocks as a small part of your portfolio.
Step 5: Automate a Monthly Amount
In expat investing, the difference between people who build wealth and people who talk about it is rarely strategy. It is consistency.
Pick a fixed amount, invest it on the same day your salary lands, and automate it where your broker allows. Buying every month through good and bad markets is called dollar-cost averaging. It works because it removes the emotional decisions that hurt most portfolios.
How much should you invest each month?
- Just starting: $100 to $300 a month to build the habit.
- Established: 15% to 20% of take-home pay.
- Aggressive: 30% or more if you are aiming for financial independence on a set timeline.
For example, $300 a month for 15 years at an average 7% annual return grows to roughly $95,000, from $54,000 of contributions. Returns are never guaranteed, but the habit is what makes growth possible.
Step 6: Understand the Tax Rules of Expat Investing
Tax worries stop more expats from investing than anything else. Here is the plain version.
- Where you live: some countries, such as the UAE, have no personal tax on investment income or capital gains. Others tax residents on worldwide income, so check your local rules.
- Where the investment is based: the US withholds tax on US dividends paid to non-residents, which is why Irish UCITS ETFs are popular with expats.
- Your citizenship: most countries tax based on residence, not passport. The big exception is the United States, which taxes its citizens wherever they live.
If you are a US citizen or green card holder, this guide is not written for you. Non-US funds such as UCITS ETFs can be treated as PFICs under US rules, which carries heavy tax reporting and costs. Speak to a US expat tax specialist before buying anything.
For everyone else, a simple ETF portfolio at a regulated broker is not complicated. Keep your annual statements, since you may need them if you move to a country that taxes investments.
Expat Investment Advice: The Offshore Plan Trap
If you search for expat investment advice, you will find many advisers offering to manage your money. Some are excellent. Many are commission-based salespeople, and their favourite product is the offshore savings plan.
These plans, often called regular savings plans, portfolio bonds or unit-linked plans, usually lock you into monthly contributions for 10 to 25 years. Fees are built into the structure and can take a large share of your returns, while the adviser often earns a big upfront commission. Stopping early can mean losing a large part of what you paid in.
Warning signs to walk away from:
- A long lock-in period with penalties for stopping or withdrawing early
- “Bonus” units or loyalty rewards in the first year or two
- An adviser who will not tell you, in writing, exactly how they are paid
- Pressure to sign quickly, often after a free “financial review” at work
A low-cost ETF at a regulated broker gives you full access to your money, lower fees and no exit penalty. If you want advice, look for a fee-only adviser who charges a clear fixed fee and earns no commission on products.
What Happens When You Move Countries?
Most expats move at least once more, so good expat investing plans for it from day one.
- Choose a portable broker. IBKR serves clients in almost every country, so your account can usually move with you. Some brokers may ask you to transfer or sell when you change residence.
- Update your details. Tell your broker when you move, as tax forms and the regulated entity can change.
- Check the tax rules of your next country before you arrive. Some countries, such as Australia and Canada, have specific rules on the cost base of investments when you become or stop being a resident. A short session with a tax adviser before you move can save a lot of money.
- Keep records. Save purchase dates and prices for every investment. Your next country may need them to calculate gains.
4 Expat Investing Mistakes to Avoid
- Waiting until everything is clear. There will always be uncertainty about your job, your visa or the market. Someone who invests $200 a month from today with a simple setup will usually be far ahead of someone who researches for two years.
- Signing an offshore savings plan. High fees and long lock-ins can quietly take a large share of your returns.
- Buying US-listed ETFs by default. They are what American guides recommend, but they cost non-Americans more in dividend tax and carry estate tax risk.
- Spending your tax-free years. If you live in a low-tax country, these are your best years to build wealth. Lifestyle inflation is the most expensive expat habit of all.
Want one practical investing tip for non-Americans every week? Join the free CentsForward newsletter below.
Frequently Asked Questions
Can I invest in the stock market while living abroad?
Yes. International brokers such as Interactive Brokers, eToro and XTB accept residents of most countries. You open the account online with your passport, residence ID and proof of address, fund it in US dollars and buy global stocks and ETFs.
What is the best expat brokerage account?
Interactive Brokers is the best overall expat brokerage account because it accepts clients from around 200 countries, has very low costs and can move with you. eToro is easiest for beginners, and XTB offers 0% commission up to €100,000 a month.
What are the best investments for expats?
For most expats, a low-cost, broadly diversified Irish-domiciled UCITS ETF is the best starting point. For halal investors, Shariah-screened options include ISWD, ISUS and ISDE. Avoid high-fee offshore savings plans.
How much money do I need to start investing as an expat?
Very little. IBKR and XTB have no minimum deposit, and eToro requires $100 for UAE residents. With fractional shares, you can start with $100 to $300 a month.
Do expats pay tax on investments?
It depends on where you live, where the investment is based and, for Americans, your citizenship. UAE residents pay no local tax on investment gains or dividends, but the US withholds 30% on US dividends paid directly to them. Irish UCITS ETFs reduce that to 15% at the fund level.
Is expat investing halal?
It can be. Buy real shares and ETFs without leverage, avoid interest by using an Islamic account or a cash account, and choose Shariah-screened funds such as ISWD, ISUS or ISDE. Check with a scholar you trust for your own situation.
Should I use an expat financial adviser?
Only a fee-only adviser who discloses exactly how they are paid. Be very careful with commission-based advisers selling long-term offshore savings plans, which often have high fees and heavy penalties for leaving early.
The Bottom Line
Expat investing comes down to a few simple moves: protect yourself with an emergency fund, open a regulated expat brokerage account, fund it in US dollars, buy a low-cost diversified ETF every month and stay away from high-fee offshore plans. The best time to start was your first month abroad. The second best time is this month.
This article is for education only and is not financial or tax advice. Rules and fees change, and your situation is unique, so check with a qualified professional before making decisions.
[…] To open any of them, you will usually need your passport, a residence visa or Emirates ID, proof of address such as a utility bill or bank statement, and a W-8BEN form, which certifies you are not a US person. Your broker handles the W-8BEN during sign-up. If you are new to all of this, start with my guide on how to start investing as an expat. […]